![Point.png]](https://www.calyxsoftware.com/hs-fs/hubfs/Point.png?height=40&name=Point.png)
Completing an Adjustable-Rate Mortgage (ARM) Loan
An Adjustable-Rate Mortgage Loan. (ARM) is a type of mortgage in which the rate increases or decreases throughout the loan schedule or until the life cap is reached.
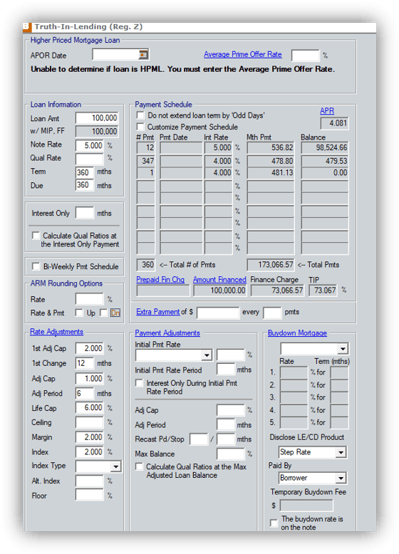
The (ARM) Adjustment is located on the Truth-in-Lending or Amortization Schedule screen.
At a minimum, the following must be completed:
- Loan Amt
- Note Rate
- Term and Due
- 1st Adj Cap
- 1st Change Mths
The life cap is the maximum note rate this loan can reach. The note rate varies depending on the margin and index rates at the time. The margin and index change often; therefore, no one can determine the exact rate six months from now. When entering the Life Cap into Point, enter the difference between the actual Life Cap and the Note Rate.
Point can only show two scenarios: the worst-case scenario and the best-case scenario. Most users choose to show the worst-case scenario to the Borrower.
Worst Case Scenario:
When disclosing the worst-case scenario on an ARM, the APR will also calculate a worst-case scenario showing an increase in the APR.
The worst-case scenario applies when we do not know what the margin and index rates will reach in the future. In this example, the note rate increases 2% after the first 12 months, then increases 1% every six months after that, until the life cap is reached.
- 1st Adj Cap – Indicates the maximum increase or decrease of the Note Rate, as it changes the first time. (For example: the Note Rate, in this example, can increase 2% over the Note Rate.)
- 1st Change – Indicates the number of months that the loan will remain fixed at the initial Note Rate. (For example, the note rate increases 2% after the first 12 months.)
- Adj Cap – Indicates the maximum percentage that the rate increases for each subsequent adjustment period, after the first. (For example, the note rate adjusts 1% after the first adjustment cap.)
- Adj Period – Indicates the frequency that the note rate will increase per the Adj Cap. (For example, the note rate will increase 1% every 6 months.)
Best Case Scenario:
When disclosing the best-case scenario on an ARM, the APR will also calculate a best-case scenario showing a decrease in the APR.
To view a best-case scenario, enter a Margin and Index. The best case occurs when we know the current Margin and Index.
This scenario assumes that the margin and index will remain the same from six months to a year from now.
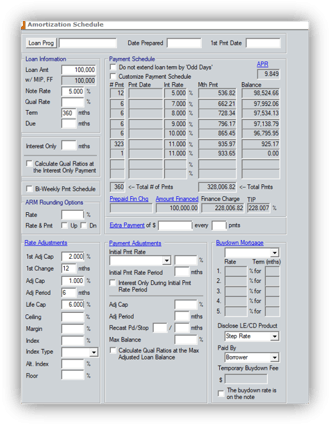
- Notice the Note Rate increases to 5.8 after the first 12 months.
- The 1st Change, Adj Cap, Adj Period, and Life Cap fields are ignored because the best-case scenario is Margin + Index = Note Rate. (In this example, the Margin is 2.3 and the Index is 3.5.)
- In this example, the Margin + Index = 5.8. Thus, the note rate after the first change of 12 months is 5.8.